Rocket Mortgage

Screenshots
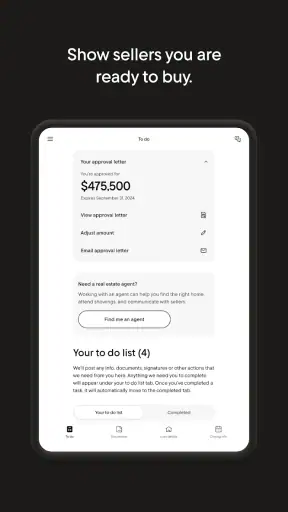
Details
- Rating
- 15.06K reviews
- Version
- 10.35.0
- Developer
- Rocket Mortgage
Analysis by Norviv
Managing a mortgage is rarely a one-person task. Even when only one borrower makes the payment, a partner may need to check the balance, a household may be planning around the next due date, and everyone benefits from knowing where the loan stands. I found Rocket Mortgage most useful in that everyday space: it puts mortgage-related account work into a finance app instead of making me depend on paper statements or a desktop browser every time I want to check something.
Developed by Rocket Mortgage, this free app is aimed at people who already have a mortgage relationship with the company and want a more convenient way to manage it. It is not a general budgeting tool, a full banking replacement, or a mortgage comparison marketplace. That distinction matters. Its value comes from bringing the loan account closer to the routines people already follow on their phones, while its usefulness depends on whether Rocket Mortgage is the company handling your mortgage.
How Rocket Mortgage fits into a shared household routine
A realistic example is a couple reviewing monthly expenses after payday. One person opens the app to check the mortgage account, the other looks at the household budget, and they decide whether an upcoming home repair can fit alongside the regular payment. In that situation, the app can reduce the small amount of friction involved in finding the latest loan information. Nobody has to search through old email, locate a statement, or wait until they are sitting at a computer.
I like this kind of use because mortgage decisions often happen in short conversations rather than formal financial meetings. A partner might ask how much remains on the loan, whether a payment has gone through, or when it is sensible to review the account again. Having the relevant account available on a phone makes those conversations easier to start. It does not replace careful financial planning, but it can make the mortgage less invisible between payment dates.
The important boundary is that a shared household is not automatically the same thing as a shared account. I would not treat the app as a communal profile that everyone should casually use with one saved sign-in. If two adults need regular access, they should rely on the account arrangements available through Rocket Mortgage rather than passing credentials around. That is both clearer and safer than turning one person’s login into a household shortcut.
This is also where the app differs from a spreadsheet or a budgeting application. A spreadsheet can combine the mortgage with utilities, insurance, groceries, and other costs, but it depends on someone entering or updating the information. A budgeting app may show a broader financial picture, yet it is not necessarily the best place to handle mortgage-specific account activity. Rocket Mortgage is narrower, but that narrow focus is exactly why it can be useful when the question is simply, “What is happening with our home loan?”
What I would do before handing over the phone
For occasional household coordination, I would open the app myself and show the relevant information rather than leave the account permanently unlocked. That approach keeps the conversation collaborative without blurring whose account is being accessed. It is especially sensible on a tablet or another device that several people use, where the next person may not be the person who last checked the mortgage.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would also avoid discussing sensitive account details in front of children or visitors just because the phone happens to be nearby. The app is rated for Everyone, which describes its store age classification, not a recommendation that every person in a household should operate an adult financial account. A child can be present while a parent manages the mortgage, but that does not make the child an appropriate account user.
Another practical habit is to check the account during a calm moment rather than while rushing to make a decision. A phone view is convenient, but convenience can encourage quick assumptions. If I were comparing payment information, planning a refinance conversation, or checking a major change, I would read the details carefully and use the company’s formal support or loan documents when the decision required more context than a compact mobile screen provides.
Setup, account boundaries, and day-to-day coordination
The first question before installing anything is simple: is my mortgage actually connected to Rocket Mortgage? If the answer is no, this is probably not the right finance app for me. Installing it will not turn another lender’s account into a Rocket Mortgage account, and it should not be judged as though it were designed to manage every mortgage from every provider.
For an existing customer, the sensible setup is to use the same account identity associated with the mortgage relationship and keep the sign-in private. I would choose a device that is protected by a screen lock and avoid saving access on a phone that belongs to the whole family. If a partner needs their own access, I would look for the proper account-level route rather than assuming that sharing one password is the intended workflow.
This boundary becomes more important when household finances are complicated. A couple may share a home but keep some financial responsibilities separate. One person may be the primary borrower while the other contributes to payments. The app can support a conversation about the mortgage, but it does not erase the legal and practical distinction between being informed about a loan and being authorized to manage it.
That is one of the less obvious trade-offs of a dedicated mortgage app. It can make information easier to reach, but it may also make the account feel more casual than it really is. A balance shown on a phone still belongs to a serious financial commitment. I found the best approach was to use the app for quick awareness and routine checks, then slow down whenever the information affected a larger household decision.
Coordination is where the app can earn a place on a family’s home screen. One person can check the account before a budget discussion, another can use the information when planning a transfer, and both can agree on when to review the loan again. The app does not need to become the household’s entire financial command center to be helpful. It only needs to remove repeated searching from the mortgage part of the conversation.
At the same time, I would not expect it to replace a shared budgeting system. If the household needs categories, spending trends, several bank accounts, investment tracking, or a combined view of all debts, a broader personal finance tool is likely better. Rocket Mortgage is strongest when the mortgage itself is the subject, not when the goal is to build a complete picture of every financial account.
Where the mobile format helps and where it gets in the way
The phone format is convenient for a quick check while planning the week or reviewing expenses away from home. It is less comfortable for extended reading, careful comparison, or work that involves several documents at once. I would use the app to orient myself, then move to a larger screen or formal paperwork when I needed to study details closely.
That distinction also affects shared-device use. A phone used by one person can make the app feel private and efficient. A family tablet can make it easier to discuss the mortgage together, but it raises the chance that the wrong person will encounter an open session or that account information will remain visible. The device environment matters almost as much as the app itself.
Another limitation is scope. A mortgage account is only one part of home ownership. Property taxes, insurance, maintenance, utilities, and emergency savings all affect whether a household can comfortably meet its obligations. I would not use a mortgage-focused app as proof that the household is financially healthy. It can show the loan side of the picture, but it cannot make the other costs disappear.
For people who prefer paper records, the app may feel less satisfying as a primary system. A digital account is quick to consult, but some users want a folder of statements or a desktop workflow for long-term organization. I see the app as a convenient access point rather than a reason to abandon every other record-keeping habit.
Trust, age context, and deciding who should use it
The Everyone age rating makes the app broadly acceptable from a store-classification perspective, but mortgage management is still an adult responsibility. I would be comfortable using it around my family with sensible privacy habits, yet I would not give a child independent access simply because the app is available to them. The relevant question is not whether a young person can open an app; it is whether they should be involved in an account tied to borrowing and home ownership.
For teenagers learning about household finances, a parent could demonstrate the general idea of a mortgage without exposing credentials or unnecessary personal details. That can turn a routine payment discussion into a useful lesson about long-term commitments. The app may serve as a visual starting point for that conversation, but it should not be treated as an educational sandbox or a shared family dashboard.
Trust also matters between adults. If a partner needs to know whether a payment was handled, showing the relevant account information may be enough. If both people need ongoing control, the correct arrangement should be established through the mortgage relationship itself. I would avoid making one person responsible for all access simply because that person installed the app first.
Privacy habits are particularly important on a device that is borrowed, repaired, sold, or shared with relatives. I would sign out when appropriate, keep the phone protected, and check what appears on the lock screen before leaving the device unattended. These are not special features I am attributing to the app; they are practical ways to use any financial application responsibly in a household.
People who are uncomfortable with mobile financial management may prefer the usual alternatives: a desktop account, statements, or direct contact with the lender. That is not a failure of the app. A mortgage is too important to force into a phone-based routine that makes the borrower uneasy. The best tool is the one the household can use accurately and consistently.
Who benefits most from this focused approach
I would recommend trying it first to a Rocket Mortgage customer who checks the loan regularly, shares home-planning conversations with a partner, or wants a quicker alternative to visiting a browser. It is also a reasonable fit for someone who wants the mortgage separated from general spending apps, rather than mixed into a crowded financial dashboard.
I would be more cautious if I were looking for a lender-neutral mortgage organizer. Someone comparing several loans, tracking a property owned through another company, or managing a complete household balance sheet will probably find a broader tool more suitable. The app’s focus is a strength for its intended audience and a limitation for everyone else.
It is also not the right choice for anyone expecting the app alone to explain complicated loan decisions. A mobile account view can help me see what is happening, but it should not be the sole basis for decisions involving refinancing, ownership changes, payment difficulties, or other high-impact matters. Those situations deserve careful review of the relevant documents and direct clarification from the mortgage provider.
Performance expectations and the app’s place among alternatives
Rocket Mortgage has been available since Aug 6, 2011, and the current version is 10.35.0. It is free to install, supports devices running operating system version 10 or later, and has passed the scale test of a widely used finance product, with over a million installs and a 4.7 average from around thirty-two thousand ratings. Those figures suggest that many borrowers find the mobile approach worthwhile, although popularity does not remove the need to judge whether it fits my own account and household.
The long availability is reassuring in one narrow sense: this is not a brand-new experiment that exists only as a promotional companion. Still, I would keep the app updated and make sure my device meets the stated operating-system requirement before treating it as my main mobile access point. A household relying on an older phone may need to use the browser or another established method instead.
Compared with calling a lender, the app is better for quick, self-directed checks. Compared with a desktop portal, it is more convenient when I am away from a computer but less comfortable for detailed review. Compared with a budgeting app, it is more focused on the mortgage and less useful for the rest of household spending. Compared with paper statements, it is easier to consult in the moment but less tangible for people who organize their finances physically.
That comparison helped me place it correctly. I would not ask one tool to win every category. Rocket Mortgage makes the most sense as the mortgage-specific layer in a household’s financial routine. A family might still use a spreadsheet for shared planning, bank tools for cash flow, and documents for records. The app’s job is to make the loan account easier to reach and discuss, not to replace every other method.
One useful habit is to separate “checking” from “deciding.” I can check the account on the phone before a household meeting, note the questions that need attention, and then make the actual decision with the right documents in front of me. This prevents a quick glance from becoming an accidental substitute for understanding the loan.
My household verdict
After using it as a mortgage-focused finance tool, I see Rocket Mortgage as a practical option for existing Rocket Mortgage customers who want easier mobile access and clearer coordination at home. The strongest benefit is not flashy functionality; it is the reduction of small obstacles between a borrower and the account information needed for ordinary planning.
I would use it for routine awareness, a partner conversation, and a quick check before organizing the month. I would keep account boundaries clear, avoid shared passwords, and remember that the Everyone rating does not turn a mortgage account into a child-friendly shared space. For a household device, I would be especially deliberate about screen locks, visible account information, and signing out when the device changes hands.
The app is less compelling for people who do not have a Rocket Mortgage account, want a complete financial dashboard, or prefer formal documents and phone support for every interaction. Those users may be better served by their lender’s existing web tools, a broader budgeting application, or direct assistance. The right reason to install it is focused mortgage access, not the expectation of a complete household finance system.
Overall, I would recommend it to the right borrower rather than to everyone. Its free availability, mature presence, and strong average rating make it easy to consider, but the real test is personal: does Rocket Mortgage handle your loan, and would quicker access improve the way your household plans? If both answers are yes, this app can become a useful, low-friction part of managing the home. If either answer is no, another financial tool will probably serve you better.
Frequently Asked Questions
01What is Rocket Mortgage, and what can I do with the app?
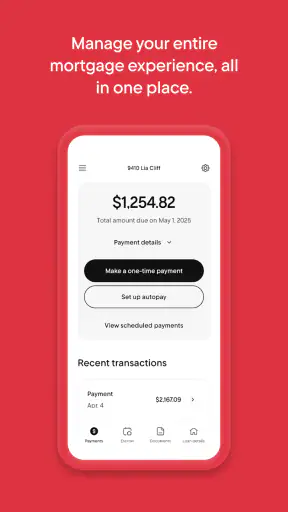
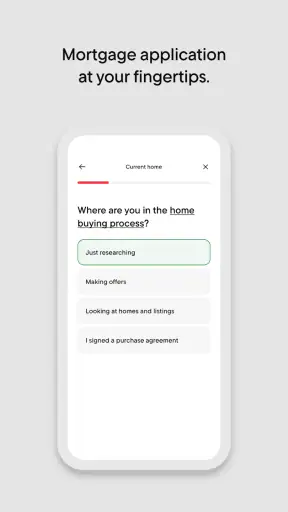
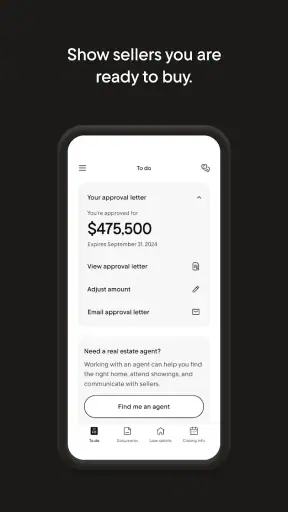
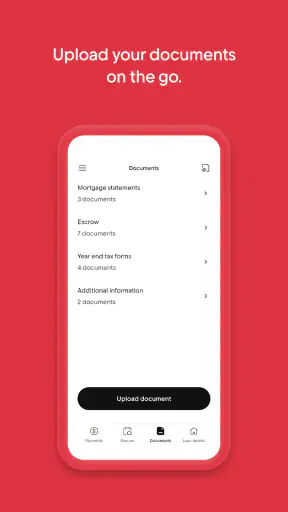
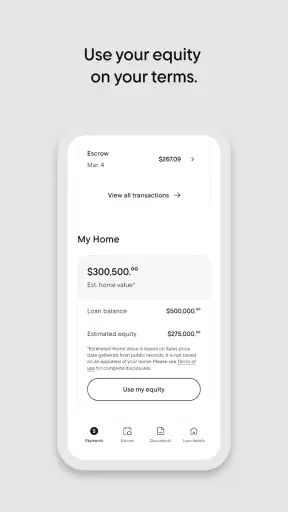
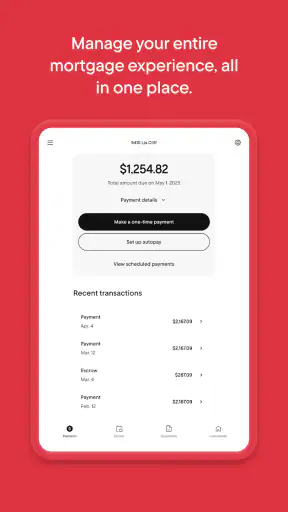
Rocket Mortgage is a mobile platform for researching, applying for, and managing a home loan. After signing in, users can review loan options, submit personal and financial information, upload requested documents, track application progress, communicate with mortgage professionals, and view updates about an existing mortgage. The exact features available may depend on your location, loan type, application stage, and whether your loan is serviced by Rocket Mortgage.
02Can I apply for a mortgage entirely through Rocket Mortgage?
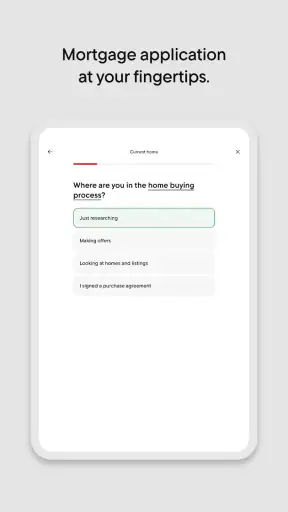
The app is designed to support a largely digital mortgage process, allowing you to begin an application, provide information, upload documents, and monitor progress from your phone. However, a completely online experience is not guaranteed for every borrower. Some applications may require additional verification, phone conversations, electronic signatures, or other documentation. Approval, rates, and available loan products depend on your finances, credit profile, property, and lending requirements.
03Is Rocket Mortgage free to download and use?
Downloading the Rocket Mortgage app is generally free, but using the app does not mean that obtaining a mortgage is free. Mortgage transactions can include interest, lender fees, closing costs, appraisal charges, title expenses, and other third-party costs. Before accepting an offer, carefully review the loan estimate and related disclosures. Also remember that eligibility, rates, fees, and promotional terms can change based on your application and current market conditions.
04Is my personal and financial information secure in Rocket Mortgage?
Rocket Mortgage uses account authentication and security measures intended to protect sensitive information submitted through its digital services. Even so, no online platform can eliminate every security risk. Use the official app-store version, create a strong unique password, enable available verification features, keep your device updated, and avoid entering account details on public or unsecured networks. Contact support through official channels if you notice suspicious activity or unexpected account changes.
05What should I check before downloading and using Rocket Mortgage?
Before downloading, confirm that the app is available in your country and that your device meets the current operating-system requirements. Review the developer name, permissions, privacy policy, and recent user feedback in the official Google Play or Apple App Store listing. You should also understand that the app provides mortgage-related tools and account access, not a guarantee of approval. Compare loan terms carefully and seek professional advice when you are unsure about a financial decision.


